KOHO Review (September 2026) – Get a $40 Welcome Bonus

*Limited time only – Get a $40 cash bonus with code: COMPAREWISE by opening an account and making a purchase with KOHO card within 30 days after registration (this works with both virtual and physical cards). Plus get 2 months of KOHO Everything FREE ($29.50 value)!

KOHO has a new plan! Meet the KOHO Core Plan. Check out our full breakdown to see what’s included and whether it’s the right fit for you. Read our KOHO Core review →

Editorial Note: Comparewise is supported by our readers. When you find products and services through links on our site, we may earn commission.

Last Updated: Sep 25, 2026

KOHO

  • Get cashback on your spending and savings
  • Get a $40 welcome bonus when you use your card
  • Get 3 months 50% off credit building

Get a $40 cash bonus with code: COMPAREWISE + 3.5% interest - Claim offer

Our KOHO review covers everything you need to know about the Fintech company. Discover the pros & cons, of their products, services, & more.

This KOHO review will explore one of Canada’s pioneering Fintech companies. We’ll discuss the products and services KOHO offers and the benefits and drawbacks of banking with them. In addition, we’ll walk you through the sign-up process.

Fintech companies like KOHO are changing the status quo of the banking industry. KOHO is giving the power back to the consumer, allowing you to make better choices for your overall financial health.

They provide three personal plans, a credit building feature, and an alternative to payday loans. Peoples Trust, a federally regulated financial institution, backs KOHO.

If you’re looking to save on banking fees, it’s time to take a non-traditional route. With KOHO, you’ll not only be able to avoid a medley of fees that easily rack up, but you’ll also earn cash back rewards.

This KOHO review will introduce you to KOHO’s products and much more. Let’s dive right in.

What makes KOHO a good option?

Before getting to the heart of our KOHO review, let’s explore why KOHO is the top choice for many Canadians. KOHO’s goal is simple: helping Canadians take control of their finances.

They achieve this by giving you access to an app to monitor spending, educational resources, and saving and budgeting tools.

You can spend, budget, save, earn cash back, rebuild credit, and more with KOHO. Since it’s not a bank, you can avoid several of the usual fees and interest to benefit from their products. Below are more reasons KOHO is a good option. 

Great credit card substitute

Getting a credit card is a rite of passage. But you may realize quickly that it’s a financial trap. According to a Canadian Financial Capability Survey, credit card debt is the second most common type of debt amongst Canadians.

The reason is that many credit card providers charge exorbitant fees to enjoy the convenience of a credit card. If you don’t pay your balance on time, you’ll be charged interest.

You also may have to pay an annual fee for your credit card. All these costs rack up, and they can leave you in an inescapable debt cycle.

That’s why people turn to the KOHO Prepaid Mastercard. It combines the conveniences of a debit and credit card.

You spend your own money, meaning you won’t have to worry about paying anyone back. Also, you don’t have to stress about racking up interest for unpaid balances.

Like some credit cards, you’ll earn cash back rewards with the KOHO Prepaid Mastercard. You can get this perk and more for no fee if you take certain steps like linking direct deposit with your account or depositing a minimum of $1,000 per month.

But, as you’ll discover in this KOHO review, there are numerous other benefits to enjoy.

Easy to use and convenient

You can use the KOHO prepaid card like a credit card, whether you’re making online or in-store purchases.

The KOHO prepaid card is reloadable by KOHO e-transfer. This means you can top up your account balance at your convenience.

What’s more, you’ll get a virtual card to use for online purchases, allowing you to avoid any fraudulent activities.

Since the KOHO prepaid card runs on the Mastercard network, it’s accepted at millions of stores. Therefore, you won’t have to worry as much about card acceptance at most merchants.

Reasonable cash back program

It’s rare to find no-fee cards that automatically enrol the cardholder into a cash back program. Tangerine and Neo Financial are two of the most well-known credit card providers offering this perk.

However, when compiling our KOHO review, we discovered that KOHO does as well.

With the Core and Extra KOHO plans, you can earn up to 1.5% cash back on eligible purchases made with your card and earn 2% interest on your savings with the Core plan and 2.5% interest with Extra. As for the KOHO Everything option, you’ll earn 2% cash bank on groceries, food and transportation and 3.5% interest on your savings.

Useful saving and budgeting features

Budgeting and saving are two essential skills everyone should have. Once you’ve built them, they can improve your financial health. The KOHO app is your best friend when looking to categorize your spending.

You can monitor your pre-set spending categories using your KOHO card to see where you’re overspending. By keeping track of your purchases, you can create better spending habits.

KOHO can help you save up for that trip you’ve long dreamt of with your family or friends. We discovered how easy it is to set up savings goals in the KOHO app when writing this KOHO review.

You’ll be able to monitor your progress and even automate your savings with the RoundUp feature.

koho cash advance - comparewise.ca

Ideal for poor or no credit

Having good credit can open up many doors for you. The opposite is the case when you have poor credit. Your application for a credit card may be declined, so you’ll have to look elsewhere.

That’s where the KOHO Prepaid Mastercard comes in. You won’t need perfect credit to be approved for this card because you spend your own money that you deposited previously.

Therefore, your credit history won’t stand in the way of accessing the conveniences of this Mastercard.

Send money abroad with ease

If you’re looking to send money abroad or convert currencies, you can save money with KOHO International Money Transfer. You’ll get access to the best exchange rates, see any applicable fees in a transparent, up-front way, and your money will arrive at its destination in 30 minutes.

Build credit while you pay rent

Normally, renters’ monthly payments to their landlords don’t count towards credit history the way credit card payments do. But that means you miss out on all of the on-time payments you make that could boost your credit score. KOHO is here to change that! You can set up your rent payments through KOHO so they get reported to Equifax and count towards your credit history.

Buy & sell crypto in KOHO

KOHO Crypto lets you trade digital assets without ever leaving the app you already use to spend and save. With trading fees from just 0.5% to 1.5% and no hidden spreads or markups, you always know what you’re paying. Start with as little as $1, buy and sell directly from your KOHO balance, and convert back to cash instantly. All coins are paired in Canadian dollars so there are no FX fees, and your assets are held securely through Ndax, a CIRO-registered platform. Simple, affordable, and built right into your everyday banking.

Pros and cons of KOHO

In this part of our KOHO review, we’ll inform you about the benefits and drawbacks of KOHO’s products and services. Here’s a brief overview:

Pros of KOHOCons of KOHO
✅ Quick and simple application
✅ Cash advances up to $500
✅ Lines of credit up to $15k
✅ Low or no fees
✅ Earn cash back
✅ Free budgeting tools
✅ Fund with e-transfer
✅ Credit building available (even report rent!)
✅ Tennant insurance available
✅ Automated savings
✅ Financial coaching available
Monthly fee waiver requires direct deposit or $1,000/month
Foreign transaction fees
No insurance perks
No investment accounts
Limited customer support

The pros of KOHO

KOHO is great for people who want to save more and earn more cash back and other perks.

Quick and simple application process

The first pro in our KOHO review relates to its hassle-free application process. Applying for a KOHO account takes less than ten minutes, and you can complete the entire process online.

Once your application is approved, KOHO issues a virtual prepaid card you can use until your physical card arrives.

Low or no fees

KOHO Core is free automatically. Which is great compared to many bank accounts with comparable cash back perks.

If you sign up for KOHO Extra or Everything, there isn’t an option for waiving the fee, but the fee is also quite low and you get increased perks with these plans so they are worth it depending on your account use. In addition, KOHO doesn’t charge the following transaction fees:

  • INTERAC e-transfers
  • Electronic fund transfers from your bank
  • Card cancellation
  • Refund processing
  • Activation

Also, KOHO ATM withdrawals are entirely free. So you don’t have to worry about racking up these charges with your KOHO card.

Earn cash back

All KOHO plans get you cash back rewards of 1%, from the Core to the KOHO Everything plan.

You won’t find this major perk with a typical debit card which is why we’ve highlighted it in this KOHO review. You’ll also receive up to 50% cash back when shopping at KOHO’s partners.

Free budgeting tools

The KOHO app is equipped with tools that make managing your money easier.

You can categorize and monitor your spending, receive real-time spending notifications, and compare your spending habits to other KOHO users. What’s more, you won’t have to pay to use the budgeting aspects of the app.

Third-party e-transfers

Another pro we’ve decided to include in this KOHO review is that KOHO lets you receive e-transfers from friends and family.

Credit building available

While the KOHO Prepaid Mastercard itself doesn’t improve your credit score, you can purchase an add-on.

Therefore, if you have bad credit, you can subscribe to the feature for a fee to improve your credit rating.

Automated savings

Say goodbye to forgetting to stash some cash away for your savings goals. With KOHO, you can automate your savings with their Roundup feature.

Every purchase you make will be rounded to the nearest $1, $2, $5, or $10; you choose which amount. The difference between the purchase price and the rounding amount you set will be transferred to a separate account.

Financial coaching available

Suppose you need some guidance with investing or managing your finances. In that case, KOHO can set you up with an accredited financial counsellor.

You can easily access your financial coach through the KOHO-app. Bear in mind that this feature is exclusive to the KOHO credit building add-ons. But we still felt that it was an important advantage to point out in this KOHO review.

The cons of KOHO

Here’s what some KOHO users had to say in terms of what could be improved about the experience.

Limited card acceptance

Some KOHO cardholders have noted that the KOHO card fails when performing certain transactions, specifically making payments over $100.

Also, the card may not work at all stores. However, this is a common issue even with prominent credit card providers like American Express.

Foreign transaction fees

Unless you have a premium account, you’ll face the standard 1.5% foreign transaction fee when making purchases in a foreign currency.

No impact on credit score

Unlike credit cards, prepaid cards don’t affect your credit score.

If you want to maintain your credit and not risk falling into a lower bracket, this is a good thing. However, it’s not ideal for improving your credit score.

Prepaid cards don’t operate with a line of credit. You’ll spend your own money, so you won’t have to pay anyone back. KOHO won’t need to report any account activity to the credit bureaus either because it has nothing to do with credit.

The good news is that KOHO offers secure lines of credit specifically to help their members build credit. Some members have boosted their score up to 22 points after just 3 months.

No insurance perks

We felt it necessary for our KOHO review to include the fact that KOHO cards don’t come with travel or purchase insurance. Also, you won’t get mobile device insurance or an extended warranty.

No investment accounts

KOHO doesn’t offer any accounts for investing long term. Therefore, it can’t wholly be a substitute for your bank. You can’t open a Tax-Free Savings Account (TFSA) or an RRSP account.

However, you can fund your investment accounts directly from your KOHO account.

Customer support issues

Some KOHO cardholders find contacting customer support through web chat futile. Also, when talking directly to someone on the phone, your issue may not be solved as quickly as expected.

Therefore, KOHO is ideal if you prefer finding solutions to issues independently.

Range of products and services

Now, let’s dive into the most critical part of our KOHO review. To anyone unfamiliar with KOHO, it may appear like a regular card you’d get from a bank. Or one that you pick up in the store to gift to a friend or relative. There’s actually more to it.

Thanks to Peoples Trust, your card is linked to an account where your money is kept safely. You also have access to an app with many valuable features. Below is an overview of KOHO’s range of products and services.

KOHO personal plans

KOHO offers three plans:

  • Core: The plan that gets you more from your everyday spending for free.
  • Extra: The plan that makes your money go even further with cash back on every purchase and high interest savings for just $144 annually ($12 per month when you subscribe annually).
  • Everything: The Everything plan means getting all the bells and whistles when it comes to your KOHO account for $177 annually ($14.75 per month when you subscribe annually).

Each account is unique in its own way. Let’s explore them further below.

Core

The KOHO Core plan is an excellent choice if you want to earn more cash back on your balance and purchases but don’t want to pay a fee. You can earn 1% cash back and 2% interest on your balance with this free account.

In addition you earn up to 6.5% cashback at selected merchants! Of course you’ll get all the great perks like unlimited e-transfers and a secure virtual and physical prepaid debit card.

Extra

The KOHO Extra plan is the definition of good things coming at a cost. This account forgoes the fee-free appeal of the KOHO Core account for better rewards and perks.

You’ll get everything the Core account offers and more. For $12 per month (or $144 every year), you can subscribe to KOHO Extra to access:

  • A higher cash back earn rate. You’ll receive 2.5% cash back on three major spending categories: groceries, transportation, and food and drink.
  • Priority user support. Forget about waiting in line for your issue to be solved. Skip to the front instead, where an agent will help you promptly.
  • No foreign transaction fees and one free international monthly KOHO ATM withdrawal. Travel abroad without worrying about racking up foreign transactions and ATM withdrawal fees.

What’s more, they can create a comprehensive, tailored plan for you based on your financial needs.

You’ll also have access to KOHO’s price matching service as a premium account holder. You can send KOHO your receipts, and they’ll search for a better deal.

If they find a merchant who offers a lower price for the product you purchased, they’ll notify you. The difference between what you paid and the item’s current price will be credited to your KOHO account.

Everything

The KOHO Everything plan takes things to a whole new level of cash back perks. With this plan you get 2% cash back on grocery, food, and transportation, up to 6.5% cash back at selected merchants, and 3.5% interest on your savings and spending balance. That’s all for a monthly fee of just $14.75 ($177 a year).

You can also get a 50% discount on credit building features, with an Everything plan you pay just $5 a month. If you send money abroad, this is the plan for you. The Everything plan comes with no FX fees and 1 free international withdrawal every month.

KOHO high-interest savings account

KOHO savings accounts are on-brand with KOHO’s mission to help Canadians improve their financial health.

This feature allows you to earn up to 3.5% savings interest annually on your entire account balance. What’s more, you won’t have to meet any minimum criteria or regular deposit requirements.

The interest earned applies to your savings and your spendable and RoundUp balances. Interest is calculated daily and paid out to your account every month. You can access what you earn at any time and use it for day-to-day expenses.

The catch with a KOHO savings account is setting up direct deposits first. Once you make your first direct deposit to your KOHO account, the ‘Earn Interest’ option will unlock. From there, you’ll start earning 3.5% savings interest annually.

Credit building

Your credit score dictates most of your credit expenditures. It comes into play when applying for a mortgage or purchasing a vehicle. Also, many credit card providers check your credit score when you apply for a credit card.

If you have a low or non-existent credit score, you’ll face several limitations. However, there’s a solution. While some people opt for secured credit cards, others look to credit-building programs.

KOHO offers a credit-building feature, the cost of Credit Building depends on your plan. You can check the pricing in-app. You’ll receive a line of credit, which you’ll pay back in regular instalments. Every payment you make will be reported to the credit bureaus. Therefore, as long as you pay what you owe on time, you’ll improve your credit score.

Cash Advance

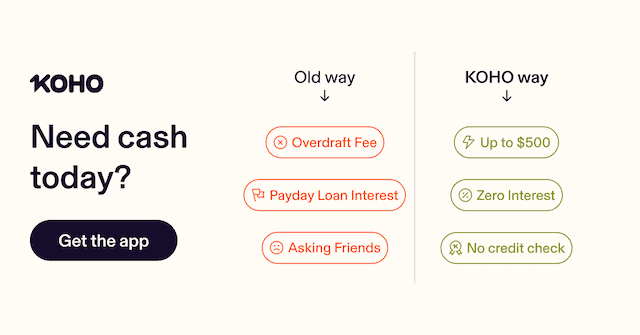
KOHO offers a cash advance feature where members can get up to $500 interest-free.

KOHO Cover is an alternative to getting a payday loan. Those loans are notorious for leading borrowers into debt cycles, so it’s best to avoid them. With KOHO Cover, you can access a $500 interest-free cash advance on your next paycheque without the risk of building debt.

This loan comes with no strings attached, meaning there aren’t fees or interest. Of course, you have to pay back the $500 you borrow, as with any other loan. However, you can pay it back quickly without the added weight of interest and charges. Just like a KOHO plan, you’ll need to set up direct deposits and add the feature through the KOHO app.

Line of Credit

KOHO offers lines of credit through Fora. You can apply and borrow $1,000-$15,000 online. Interest rates for what you borrow start at 19.99%, but you only get charged if you use the line of credit.

It’s easy and speedy to apply from the KOHO app and get your money quickly. This product is great for preparing for a big expense that comes up unexpectedly. You can have your line of credit open and not use it until you need it.

Buy Now, Pay Later Instalment Plans

With KOHO you can delay paying full price for purchases over $100, up to $1,000/month. How it works is you chose a past purchase in the KOHO app, select your payment term, and pay in smaller amounts.

Payment terms are 3, 6, or 9 months. And best of all, applying doesn’t require a credit check. So it’s super quick and won’t affect your credit. There’s no interest charged for this service, just a small fee.

KOHO International Money Transfer

  • Available to 190+ countries.
  • No surprise fees, competitive FX rates.
  • Fast delivery, money arrives in 30 minutes.
  • Included in all KOHO plans (Core, Extra, Everything).

KOHO International Money Transfer offers a fast, secure, and affordable way to send money across borders directly from your KOHO account.

Designed with user convenience in mind, the service integrates seamlessly into the KOHO app, allowing users to transfer funds internationally with just a few taps.

Whether you’re supporting family overseas or managing global expenses, KOHO ensures competitive exchange rates and low fees, making international transfers simpler and more transparent than ever.

KOHO Crypto

KOHO Crypto makes it easy to enter the world of digital assets without ever leaving the app you already use to spend and save. With some of Canada’s lowest trading fees, just 0.5% to 1.5% depending on your plan, and no hidden spreads or markups, you always know exactly what you’re paying.

You can get started with as little as $1, buying and selling directly from your KOHO Spendable balance and converting back to cash instantly, no juggling between apps or waiting on transfers. Trade popular coins like Bitcoin, Ethereum, Solana, and more, all paired in Canadian dollars to avoid FX fees.

Security is built in, with assets held in cold storage and other regulated custodial arrangements through Ndax, a CIRO-registered platform, backed by multi-factor authentication and institutional-grade encryption. Whether you prefer to set up automatic recurring purchases or price alerts to stay on top of the market, KOHO Crypto gives you a simple, regulated, and affordable way to trade, right alongside your everyday banking.

The KOHO app

A KOHO review wouldn’t be complete without looking at the KOHO mobile application. The KOHO app is all about making banking more manageable for you.

It boasts a user-friendly and aesthetic design synonymous with the youthful theme of KOHO’s website and prepaid Mastercards. Through the KOHO app, you can:

  • Track your spending. Categorize your purchases to see where you might be overspending. You’ll receive real-time spending insights on the app, allowing you to adjust your spending habits.
  • Automate your savings. Set up your account to transfer a specific amount to your account daily, weekly, or monthly.

What’s more, the KOHO app is great for automating your bill payments. That way, you will always pay your bills on time. You can also transfer money to any investment account from the app.

And you can set up payroll deposits. The KOHO app is available to download for Android and iOS devices.

KOHO product and service quality

For our KOHO review, we sourced feedback left by current and former KOHO clients from Google My Business and Facebook. KOHO has a rating of 4.4 out of 5 on Google My Business, with over 900 reviews. And a rating of 3.2 out of 5 on Facebook.

Many positive reviews remark on how helpful KOHO has been for managing finances and mitigating overspending. “A very good substitute for a credit card,” said one reviewer. Others commended the KOHO app, dubbing it user-friendly.

In a few reviews of KOHO, reviewers mention how easy it is to use the app. Some reviewers remarked on KOHO’s convenience and flexibility. And one reviewer mentioned that it’s a great alternative to their regular bank account.

Since no company is perfect, we anticipated finding less-than-positive KOHO reviews. Most reviewers were dissatisfied with the options available to reach customer support. Also, some queries took longer than expected to resolve.

We noticed with the lower-rated feedback that KOHO’s team is dedicated to finding solutions for their customers. On Facebook, they reply to all reviews—positive and negative.

Judging from the hundreds of reviews, we conclude that KOHO is worth the bet. However, you may get along better when relying on the resources available on their website to solve issues.

KOHO referral program

KOHO offers a good referral program. If you refer someone to KOHO, you’ll both earn $20. You’ll receive a unique KOHO referral code that you can share with a friend.

Once they sign up and make their first purchase within 30 days of registration, you’ll receive the referral bonus.

You can refer up to 50 people, which shouldn’t be too hard to achieve since you both earn $20. This means you can earn almost $1,000 from referrals.

One condition of the KOHO referral program is that your account must be in good standing. In the next section of our KOHO review, we’ll guide you through signing up for a KOHO plan.

How to get started with KOHO

This part of our KOHO review will show you how to get a KOHO card. Note that before you get a KOHO card, you must open an account first.

You will keep your money in this account and be able to carry out withdrawals and transfers. Your KOHO card can then be used for in-store and online purchases.

Applying for a KOHO account is straightforward. Simply visit the KOHO website, then fill out your details to set up a login.

Once that’s done, you’ll begin your application and follow these steps:

  1. Complete your personal details. Enter your legal first name, last name, and date of birth.
  2. Enter your mobile number.
  3. Fill in your street address. You can use the in-built search feature to make it easier.
  4. Enter your occupation.
  5. Choose the product or service you’re interested in. This can be spending, saving, credit building, or early pay.
  6. Review the legal information, enter a referral code, and submit if you have one.

Once your account is registered and approved, KOHO will give you a virtual prepaid card. You can use this card to make purchases through the KOHO app immediately.

Eligibility criteria

Besides being the legal age (18 or 19 years old), you will be required to verify your identity. Therefore, have at least two of the following documents handy when completing your application:

  • Bank statement
  • Passport
  • Driver’s license
  • Utility bill
  • Work permit

Alternatives to KOHO

While KOHO is great, it doesn’t offer the full spectrum of banking options your bank may offer. Perhaps you want to invest in a retirement account.

Or maybe you want a credit card instead of a prepaid card. This section of our KOHO review will help you find a suitable alternative.

KOHO vs Tangerine

Tangerine is a digital bank with a similar philosophy to KOHO which is why we’ve included it in this KOHO review.

They aim to disrupt conventional banking standards by charging no banking fees. What’s more, they provide generous interest rates for savings and investments. They offer:

  • Savings accounts
  • Chequing accounts
  • Credit cards
  • Guaranteed Investment Certificates (GICs)
  • Investment funds

Tangerine Savings Accounts carry 0.10% interest, roughly the same as a KOHO savings account. The 1.5% earned on your spendable, RoundUp, and savings balances is a yearly figure. Per month, it’s 0.10%. To learn more about Tangerine, read our Tangerine review.

KOHO Vs Tangerine

KOHO FeaturesTangerine Features
– Offers prepaid cards
– Earn 1% cash back or 2% cash back with a premium on three spending categories
– No long-term investment accounts
– No insurance benefits
– Money held with Peoples Trust
– Offers credit cards
– Earn 2% cash back on two chosen spending categories and 0.5% on everything else
– Long-term investment accounts available
– Travel insurance benefits are available
– Money held with Tangerine Bank

KOHO vs Wealthsimple

If you’re looking to step up your investment game, Wealthsimple is the ideal choice. Wealthsimple is a Canadian Fintech company that provides the following products:

  • Wealthsimple Invest: for investing in Exchange-Traded Funds (ETFs).
  • Wealthsimple Cash: for earning interest on deposits and spending your own money.
  • Wealthsimple Trade: to buy and sell stocks.

There are many other services Wealthsimple offers, but these are the most popular. Wealthsimple cash is comparable to KOHO’s personal accounts. It carries no monthly fees and no ATM withdrawal fees. The Wealthsimple Cash Card runs on the Visa network, and you can add it to Apple Pay.

wealthsimple 970x250 - comparewise

In addition, both Wealthsimple and KOHO have a RoundUp feature, where the change from your purchases is saved. With KOHO, the change is stored in a RoundUp account that earns interest, whereas, with Wealthsimple, it’s invested. To learn more about Wealthsimple, read our Wealthsimple review.

KOHO Vs Wealthsimple

KOHO FeaturesWealthsimple Features
– 1.5% foreign transaction fees (waived on premium)
– 2% savings interest on all account balances
– $20 referral program
– No foreign transaction fees
– No savings interest
– $10 referral program

KOHO vs Mogo

Mogo is a Fintech company revolutionizing financial services in Canada. They offer various services and innovative financial products, including the MogoCard. The MogoCard is a prepaid Visa card that earns cardholders 50 satoshi rewards.

What prompted us to include Mogo in our KOHO review is its focus on sustainability. Whenever you use your card, Mogo will plant a tree.

Therefore, you can offset your carbon footprint merely with your spending. Besides this, both KOHO and Mogo cards have no monthly fee.

Mogo claims that users have saved an average of $201 per month thanks to the MogoCard. This makes sense when you look at the low fees charged on the MogoCard. Read our review of Mogo here to learn more.

mogo card category - comparewise

KOHO Vs Mogo

KOHO FeaturesMogo Features
– Earns you cash back rewards
– Paid credit score monitoring
– 1.5% foreign transaction fee (Waived with premium)
– No environmental rewards
– No effect on your credit score
– Earns you bits of bitcoin (satoshi rewards)
– Free credit score monitoring
– 2.5% foreign transaction fee
– Environmental rewards
– Affects your credit score

KOHO vs Stack

Stack is a Canadian Fintech company with a digital-first approach to financial services.

It’s one of a few companies that offer a product similar to the KOHO Prepaid Visa Card: the Stack Prepaid Mastercard. Both KOHO and stack charge no monthly fees on the account attached to the card.

In addition, they both hold your money at Peoples Trust. You’ll get similar RoundUp and Stack features. Check out the table below of KOHO Vs Stack to see how the two companies measure up.

stack-promo-comparewise

KOHO Vs Stack

KOHO FeaturesStack Features
– Prepaid card runs on the Visa network
– 1.5% foreign transaction fee (waived with a premium account)
– 1% cash back or 2% cash back with premium (and up to 6.5% cash back at select partners)
– Available in the whole of Canada
– Paycheque advance 3 days early (or pay for any time before then)
– Prepaid card runs on the Mastercard network
– No foreign transaction fees
– No cash back program
– Not available in Quebec
– Paycheque advance 2 days early

KOHO review conclusion

KOHO is the ideal choice for many Canadians because it combines the best of debit and credit cards. With the KOHO card, you don’t have to worry about racking up banking fees when you use your card. The Core plan comes with a free account and card.

While saving on banking fees, you’ll earn cash back rewards. You’ll access their cash back program, whether you have a personal account for yourself or one that you share with someone.

What’s more, KOHO offers other features like a savings account. This allows you to earn up to 3.5% interest on your spendable, RoundUp, and savings balances.

And like it couldn’t get any better, you can easily get a cash advance on your paycheque of up to $500. This small loan comes without the shadiness of a payday loan.

Also, if you’re looking to build credit, KOHO has you sorted with their credit building feature. All you have to do is sign up, pay a small fee, and watch your credit score grow.

Fintech companies like KOHO are making it possible for several Canadians to take control of their finances. Their mobile app has several useful tools that you can use to improve your budgeting. What’s more, you can set saving goals in-app and work towards them by automating your savings.

You might also like…

Top offers this month

Get a $40 Welcome Bonus

Discover Investment Opportunities

Make your money do more.

12 Results

Advertiser disclosure

Offers shown here are from third-party advertisers. We are not an agent, representative, or broker of any advertiser, and we don’t endorse or recommend any particular offer. Information is provided by the advertiser and is shown without any representation or warranty from us as to its accuracy or applicability. Each offer is subject to the advertiser’s review, approval, and terms. We receive compensation from companies whose offers are shown here, and that may impact how and where offers appear (and in what order). We don’t include all products or offers out there, but we hope what you see will give you some great options.

Young investors can trade stocks and ETFs, all for free.
Min Investment
$0
Target Return
Varied
Get up to $2,200 in welcome rewards
Min Investment
$1
Target Return
Varied
Invest in a 3.25% 5-year GIC today.
Min Investment
$500
Target Return
4.90%
Flexibility with a great return.
Min Investment
$100
Target Return
5.05%
Get up to $150 cash bonus
Min Investment
$0
Target Return
Varied
High return on a shorter term.
Min Investment
$500
Target Return
4.25%
Sign up & Get $20 in BTC
Min Investment
$1
Target Return
Varied
Buying and securing gold has never beeng more simple and affordable.
Min Investment
$1
Target Return
Varied
Buy and sell gold, silver & platinum online at the best price.
Min Investment
$1
Target Return
Varied
Retire up to 30% wealthier with Questwealth Portfolio.
Min Investment
$1
Target Return
Varied
Get a $100 welcome bonus, when you make your top-up*
Min Investment
$10
Target Return
Varied
Get $25 bonus with code: 9APOU9
Min Investment
$1
Target Return
Varied

FAQs about KOHO

Is KOHO a Bank?

No, KOHO isn’t a bank. KOHO is a financial technology company, meaning it leverages technology to provide financial services to consumers. Since it’s not a bank, it offers some leeway with fees. For instance, you won’t pay a monthly fee when you open an account. Also, you won’t be charged for certain transactions like ATM withdrawals. Given that KOHO doesn't have the facilities of traditional banks, your deposits are held by Peoples Trust. They'll guard the money in your account and ensure it's safe. What also makes KOHO different from a bank because they don't have a physical branch.

Who Are KOHO Accounts Best Suited for?

KOHO is suited for a wide variety of people, so almost anyone can benefit from the prepaid Mastercard. However, KOHO is ideal if you cannot get a regular credit card. You won't have access to a line of credit, but you will benefit from a great cash back rewards program. Also, your credit score won't play a role in your chances of approval because it's not a credit product. A KOHO account is also suitable for anyone who wants to monitor and control their spending. Building good spending habits is made easier with the KOHO app. Also, since you’re spending your own money, it’s easier to not overspend.

Is It Safe to Bank With KOHO?

Absolutely. Although KOHO isn’t a bank, it’s affiliated with institutions that hold it to the standards of traditional banks. Peoples Trust holds the money you load onto your card. It’s a federally regulated financial institution registered with the Canada Deposit Insurance Corporation (CDIC). The CDIC is a federal Crown corporation. It protects eligible deposits held at CDIC member institutions from defaults by the member. The CDIC safeguards up to $100,000 for each beneficiary named in a trust. In addition, the KOHO Prepaid Mastercard is covered by Mastercard insurance. This means you’re protected from unauthorized use of your card. Also, KOHO is backed by the National Bank of Canada, Greyhound Capital, and Drive Capital.

How Is KOHO Different from a Debit Account?

KOHO accounts come with low or no fees, unlike debit accounts. The bank will charge you for various reasons with a regular debit account, including maintenance and transactions. These costs can make holding a debit account expensive, especially if you don't maintain a balance high enough to absorb the charges. The KOHO accounts flip the script by carrying no monthly fees. Most transaction fees are also waived, so you can make ATM withdrawals without worrying about charges. Also, with KOHO, you get a prepaid Mastercard that earns cash back on all purchases. You’ll not likely find this reward with a debit account.

Should I Still Have a Regular Bank Account and a KOHO Account?

Yes. While KOHO is an excellent substitute for a regular bank account, it lacks in some areas. For one, you can't open investment accounts. Therefore, if you want a Tax-Free Savings Account (TFSA) or a Registered Retirement Savings Plan (RRSP), you’ll have to look elsewhere. Also, if you still rely on writing paper cheques, KOHO can’t replace a regular bank. It’s also not ideal if you don’t want your entire paycheque deposited into your KOHO account. In this case, you’d still need a regular bank account. Despite the limitations, you can use your KOHO account to pay your bills and make unlimited free e-transfers.

How Does KOHO Work?

Using your KOHO account, the card attached, and the KOHO app is pretty simple. You fund your KOHO account by making an e-transfer from your existing bank account. Alternatively, you can have your paycheque deposited directly into your account. Once your account has funds, you can use your Mastercard for purchases in person and online. So if you were wondering how to load a KOHO card, it’s pretty straightforward. As for the KOHO app, you can use it to track your spending at a glance. Also, it’s great to set up savings goals and watch your cash back accumulate.

How Does Credit Building Work?

Once you register for KOHO’s credit building program, they perform a soft credit check. This check may not affect your credit score. There will be a slight decrease in your credit score if it does. You’ll then take out a credit-building line of credit. As you repay the line of credit on time, KOHO will report your payments to a major credit bureau. These reports will update your credit history, allowing your credit score to improve. However, if you don't make your payments on time, you'll undo all your work to improve your credit score. It will decrease, and you may end up having to start from a worse place than before.

How Does KOHO Make Money?

This is a reasonable question, given that KOHO charges no or extremely low fees. You may be worried about hidden costs, but you can rest assured that KOHO doesn’t charge any. They receive a portion of the commissions Mastercard earns from merchants whenever you use your card for a purchase. This commission is known as an interchange fee. Besides the commission, KOHO makes money through its paid services. For instance, a premium account costs $14.75 per month. The credit building service is available to users for $10 per month. Also, you pay $5 to receive an advance on your paycheque early through Early Pay Instant.

What Fees Does KOHO Charge?

There are some fees associated with KOHO plans. These include a $12 monthly fee for KOHO Extra, and a $14.75 monthly fee for KOHO Everything.

Is the Prepaid Mastercard Worth It?

That depends on you and your spending habits. It’s worth betting on if you don’t want to deal with credit. Also, if you can’t get a regular cash back credit card, it’s the next best alternative. The approval requirements are minimal, so almost everyone can qualify for the card. What’s more, you’ll earn 2% cash back without the financial burden that comes with credit cards. However, the KOHO Prepaid Mastercardard isn’t great if you want to improve your credit score without paying a fee. Your account activity won’t be reported to credit bureaus because it doesn’t constitute credit transactions.

June 5, 2024
Fact Checked
Categories:

You may also like

*Limited time only – Get a $40 cash bonus with code: COMPAREWISE by opening an account ...
Pet insurance is becoming increasingly popular in Canada as pet owners look for ways to...
Term life insurance in Canada has become much more streamlined in recent years, with mo...
In a world where online shopping dominates how people buy everything from clothes to el...
**Limited Time Offer: Get an exclusive $25 welcome offer when you sign up for the Neo C...
Car loan?
Personal Loan?

Top deals await you just a short
application away!